
Mortgage Broker in Butte, MT

Butte is the most affordable real market left in Montana. The median home sold for about $299,000 in August 2026, and homes are taking roughly 70 days to sell. In a state where Bozeman clears $700,000 and Kalispell has passed $520,000, Butte is where a working household can still buy a house on a normal income. Montana Mortgage Company compares loan options from multiple lenders so you see real rates and real terms side by side, not whatever a single bank happens to offer that week.

Multiple Lenders Compared, Not One Bank·Purchase & Refinance Across All Price Points·FHA, VA, USDA, Conventional, Renovation, Construction
Local & Direct

You call Scott, not a queue

Full Loan Menu

FHA, VA, USDA & more

From Start to Close

No rotating representatives

Montana Owned & Based

Statewide service

Butte Montana buyers reviewing renovation loan options for an older home with a local mortgage broker

The Butte Market

Why Getting a Mortgage in Butte Is More Complicated Than It Looks

At a $299,000 median, affordability is not the constraint in Butte. Property condition is. And the mismatch between those two facts is where most Butte deals go sideways.

Uptown Butte holds one of the largest concentrations of historic architecture in the American West, and much of the city’s housing predates 1978 by a wide margin. When you finance a house of that vintage with an FHA or VA loan, the appraisal is not just a valuation, it is a condition inspection against program standards. Lead-based paint requirements apply to anything pre-1978. Roofs, knob-and-tube wiring, original plumbing, failing foundations and heating systems at the end of their service life all show up regularly, and any one of them can stop a government-backed loan.

This is why renovation lending matters more in Butte than in any other Montana market. A house priced at $180,000 that needs $60,000 of work is not a problem to be avoided, it is one of the better value propositions in the state, provided you finance it correctly. An FHA 203(k) or a Fannie Mae HomeStyle loan wraps the purchase and the renovation into one mortgage at one closing, based on the value of the home after the work is done. Buyers who do not know that product exists look at the same house, see a failed inspection, and walk away from a deal that was workable.

The third factor is the appraisal itself. In a market with lower transaction volume and highly varied housing stock, comparable sales are harder to pin down than in a subdivision of similar homes. Appraisals in Butte come in low more often than they do in newer markets, and knowing that going in changes how you structure an offer and how much cash cushion you want to hold.

Loan Options

Butte Home Loan Options Matched to Your Situation

Butte’s affordability, its historic housing stock, and genuine rural eligibility just outside the urban core mean the right loan program is rarely obvious from the outside. Buyers arrive with different combinations of income, savings, service history and property targets, and matching those variables to the right product is where the financing work actually happens.

FHA financing allows as little as 3.5% down with flexible credit requirements. The Silver Bow County limit is $541,287 for 2026, far above anything you are likely to buy here, so the limit is effectively irrelevant in Butte. What is very relevant is the appraisal standard, which is stricter than conventional and matters a great deal on older homes. When an FHA appraisal flags a condition, the FHA 203(k) is usually the answer rather than a different house.
Conventional loans can go as low as 3% down for qualified first-time buyers, and private mortgage insurance drops at 20% equity rather than persisting for the life of the loan. Conventional appraisals are also more forgiving on property condition than FHA or VA, which in Butte is sometimes the deciding factor rather than the rate. For a borrower with solid credit looking at an older home, conventional can simply be the path of least resistance.
VA financing offers zero down and no monthly mortgage insurance for eligible veterans, active-duty servicemembers and qualifying surviving spouses. On a $299,000 median that means buying with essentially no cash into the property. VA appraisals apply Minimum Property Requirements, so on Butte’s older inventory the VA renovation loan is frequently the better tool than the standard VA purchase loan. Montana also administers a state Veterans Home Loan Program that can layer benefits on top of federal eligibility.
USDA-backed financing provides 100% financing with no down payment in eligible rural areas, and parts of Silver Bow County outside the urban core qualify. Eligibility is set by property address rather than by town, so check specific listings early instead of assuming. Household income limits also apply relative to area median income, and in a market at Butte’s price point more buyers clear those limits than in western Montana.
For homeowners aged 62 or older, a Home Equity Conversion Mortgage converts equity into accessible funds without a monthly mortgage payment. Butte has many long-tenured owners in homes held for decades. The counseling requirement built into the HECM process ensures borrowers understand the obligations that remain, including property taxes, insurance and maintenance. It is a specialized product with real trade-offs, and I will tell you when it is not the right answer.
Refinancing can lower your rate, shorten your term, or fund a renovation on a home you already own. Given the age of Butte housing, a cash-out refinance to fund needed work is a common and often sensible use here, particularly for owners who bought before recent appreciation. I run the break-even math with you first, including what the cash-out costs against what it accomplishes.
Butte is one of the best markets in Montana for Montana Housing programs, because the Regular Bond Loan Program, MBOH Plus, Bond Advantage down payment assistance and the Mortgage Credit Certificate all carry purchase price caps that local prices sit comfortably beneath. Income caps still apply. First-time generally means you have not owned a home in the past three years, with exceptions for veterans and certain target areas.
A construction to permanent loan funds a build through a draw schedule tied to project milestones, then converts to your permanent mortgage without a second closing and a second set of costs. For buyers who want new construction rather than a restoration project, this is the route. Builder documentation and licensing, the draw schedule, and rate lock length against a shifting build timeline are the pieces that matter most.
Manufactured home financing works through FHA Title II, conventional financing with appropriate foundation certification, and USDA in eligible areas. The first question that determines which programs apply is whether the home sits on owned land or a leased lot, followed by foundation type, whether the title has been retired, and the age of the unit. Clarifying that early prevents weeks spent pursuing a loan type that was never going to work.
Pre-approval means full income and asset verification, a credit review, and a lender commitment to a specific amount subject to appraisal. Pre-qualification is an estimate based on self-reported numbers. At 70 days on market you have time, but the well-maintained homes still move quickly, and a documented pre-approval is what makes a seller take you seriously when a property draws more than one offer.
Renovation loans are the most important product on this page for Butte buyers. They finance the purchase and the improvements in one mortgage based on after-improved value, which is what turns Butte’s affordability into actual opportunity rather than a listing you have to walk away from. The scope of work you plan determines which product fits, and that conversation is worth having before the offer goes in.
Fannie Mae’s HomeStyle loan finances a wide range of improvements on conventional terms, including work FHA’s rehab program will not cover, and it allows luxury and structural improvements the 203(k) limits. For a Butte buyer with solid credit taking on a substantial restoration in Uptown or on the hillside, this is often the strongest option available.
The FHA 203(k) combines purchase and renovation into one FHA mortgage at 3.5% down. The Limited 203(k) handles smaller cosmetic work up to a defined threshold. The Standard 203(k) covers structural and major rehabilitation. On a Butte home where lead-based paint, an aging roof, or outdated electrical would fail a standard FHA appraisal, the 203(k) is the difference between a dead deal and a closed one. This is the workhorse product in this market.
The VA renovation loan lets eligible veterans buy a home needing work with zero down and finance the repairs into the same loan, preserving the core VA advantage even when the property is not move-in ready. Very few Montana lenders offer it, and in a market where most inventory needs something, it is worth asking about by name rather than assuming a standard VA purchase loan is your only option.
Freddie Mac’s CHOICERenovation finances improvements as part of a purchase or refinance for borrowers who qualify conventionally, and it explicitly includes resilience improvements such as roofing, structural reinforcement and energy efficiency upgrades. On Butte’s older housing stock those categories cover a lot of what actually needs doing.

Neighborhoods

Butte Neighborhoods and What Buyers There Are Navigating

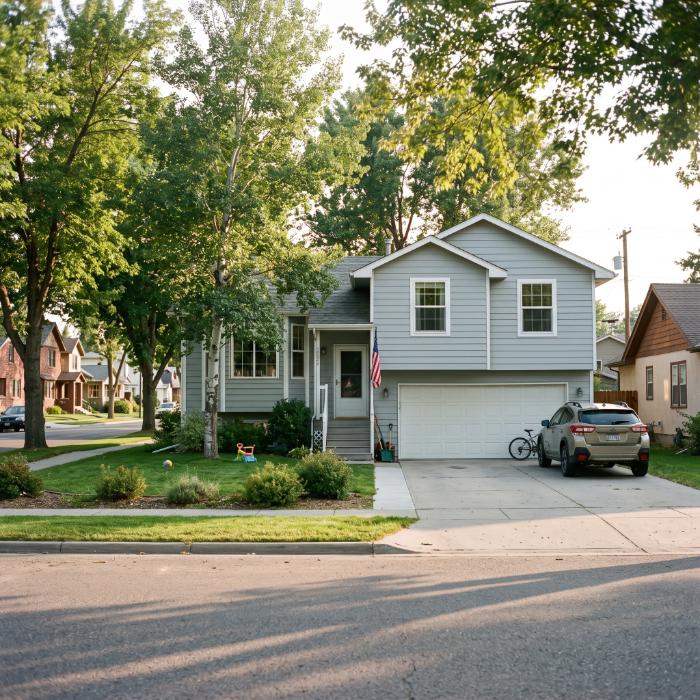
Butte is not one market. What works financing-wise in a newer subdivision on the Flats does not necessarily work on a pre-1900 property Uptown, and buyers who understand that walk in with realistic expectations rather than a surprise at the appraisal.
The most architecturally significant housing in the state and the most demanding to finance. Expect pre-1978 construction as the rule rather than the exception, original systems in many homes, and appraisals that flag conditions a newer house would never surface.

This is renovation loan territory from the start, not as a fallback. Buyers who come in with a 203(k) or HomeStyle pre-approval already in hand can move on properties that others simply cannot touch, which is a real competitive advantage in a segment where the best-value listings are usually the ones needing the most work.

The practical sequence matters here. Get the address in front of a lender before you write, so the scope of work and the loan product are settled rather than discovered. That also strengthens your position on price, because a seller who knows the property will not pass a standard FHA appraisal has fewer alternative buyers than they might think.

Generally newer construction than Uptown, more conventional subdivision layouts, and considerably more straightforward financing. Appraisal surprises are rarer, and the comparable sales an appraiser needs are easier to find.

Buyers here are usually comparing FHA against low down payment conventional on total monthly cost rather than working around property conditions. With the Silver Bow County FHA limit sitting far above local pricing, both programs are genuinely available to most buyers, which makes this a decision about long-term cost and mortgage insurance treatment rather than about qualification.

For first-time buyers, this is also where Montana Housing programs tend to fit most cleanly, because the properties are more likely to pass program condition standards without additional work.

Older housing and steeper terrain, with the same pre-1978 considerations that apply Uptown. The additional factor here is topography.

Foundation and drainage conditions come up more often on hillside properties, and those are exactly the categories that a government-backed appraisal takes seriously. Retaining walls, grading and water management around the foundation are worth looking at closely before you are under contract, because they can be expensive to remediate and they can hold up a closing.

Renovation financing applies here for the same reasons it applies Uptown, and the CHOICERenovation product is worth a look specifically because it covers structural reinforcement and roofing as eligible improvements.

Larger parcels, well and septic systems in many cases, and the genuine possibility of USDA eligibility. Zero down financing is available on some of these addresses for buyers who assumed they needed at least 3.5%.

Eligibility is set at the property address rather than the town, so check the specific listing rather than assuming based on where it sits on a map. Household income limits apply as well, and both need confirming before you plan around the program.

Well and septic systems introduce inspection requirements that city buyers do not face. Those are routine and manageable, but they add steps and time to a closing, and they occasionally surface repair conditions of their own that need negotiating with the seller.

Montana home representing the statewide service area a Butte mortgage broker covers for buyers and homeowners

Regional Coverage

Serving Butte and Statewide Montana

Montana Mortgage Company works with buyers and homeowners across the state, not just inside Butte city limits. If your search extends into Walkerville, the surrounding Silver Bow County, or toward Anaconda and the wider region, if you are relocating to or from another Montana market, or if you own a second property elsewhere in the state, one broker relationship handles all of it. I also serve Missoula, Billings, Bozeman, Great Falls and Helena. The multi-lender comparison approach does not change based on where the property sits: real rates and real terms from multiple lending partners so you can decide with the full picture in front of you.

Frequently Asked Questions About Mortgages in Butte

Conventional loans generally look for above 620, FHA can work down to 580 with 3.5% down, and VA and USDA set no federal minimum though lenders typically want 580 to 620. Because Butte prices are low, the dollar impact of a weaker score is smaller here than anywhere else in Montana. A 620 borrower buying at $250,000 in Butte is in a very different position than a 620 borrower buying at $700,000 in Bozeman. That said, if your score is sitting just under a threshold, moving it up before you apply is usually worth the short wait.
Sometimes in as-is condition, often not. Homes built before 1978 bring lead-based paint requirements into FHA and VA appraisals, and Uptown inventory frequently has roofing, electrical, plumbing or heating conditions that will be flagged. That does not mean you cannot buy the house. It means the right product is probably an FHA 203(k) rather than a standard FHA loan, so the work gets financed into the mortgage instead of becoming a condition you have to solve before closing. Send me the address and I will tell you which way it is likely to go.
You buy the home and finance the improvements in a single mortgage, and the loan is underwritten against what the home will be worth after the work is done rather than what it is worth today. A licensed contractor provides a bid, the lender approves the scope, and funds are released in draws as the work is completed. It takes longer than a standard purchase and involves more paperwork. In Butte it is also frequently the only way to buy the house you actually want, which is why the extra steps are worth it.
Yes. The median sale price was about $299,000 in August 2026, against roughly $340,000 in Great Falls, $440,000 in Helena, $525,000 in Kalispell and well past $700,000 in Bozeman. That gap is the reason people are moving here and the reason buying makes sense for households priced out of western Montana. Just budget honestly for condition, because the price difference partly reflects the age of the housing rather than pure bargain.
Practically, no. The 2026 conforming limit in Silver Bow County is $832,750 and the FHA limit is $541,287, both far above what you would spend on a typical Butte home. Unlike Kalispell or Bozeman, no Butte buyer is bumping into a ceiling. Your decision is entirely about which program fits your credit, your available cash and the condition of the house you want.
A straightforward purchase runs 30 to 45 days from application. A renovation loan runs longer, often 45 to 60 days, because the contractor bid and scope approval add steps before the file can close. Appraisals can also take longer in Butte than in higher-volume markets, and low appraisals are more common given the varied housing stock. I build realistic timelines rather than optimistic ones, because your closing date is what your move depends on.
I am based in Missoula and licensed across Montana, so Butte and Silver Bow County get the same direct line and the same loan programs, with me handling the file start to finish. Renovation lending in particular benefits from working with one person throughout, because there are more moving parts and more points where a handoff loses information. Most of my clients outside Missoula handle everything by phone, email and video.

Next Step

See Real Rates from Multiple Lenders on Your Butte Loan

Whether you are buying your first home in Butte, looking at an Uptown property that needs real work, using a VA benefit, or refinancing to fund a renovation on a home you already own, the first step is a straightforward conversation. One application, multiple lenders compared side by side, rates and fees explained in plain language. Reach out through the form below, or call (406) 880-5155 directly, and let us look at what actually fits your situation.

Licensing & Disclosures

Montana Mortgage Company is the personal brand of Scott Lucier, a licensed mortgage loan originator. Loans are originated through loanDepot.com, LLC (NMLS ID #174457), an Equal Housing Lender. Scott Lucier is licensed to originate mortgage loans in Montana and North Dakota. NMLS ID: 1637174. This is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and program availability. Equal Housing Opportunity.