
Manufactured Home Loans Missoula MT
Manufactured, modular, or mobile, the terms matter for financing. Montana Mortgage Company helps Missoula buyers and homeowners sort out which loan program actually applies to their home and get financed accordingly.
·Licensed Montana Loan Originator
·Direct Access, No Call Centers

FINANCING FOR MANUFACTURED HOMES
Manufactured Home Loans and FHA Loans for Mobile Homes in Missoula, MT
Manufactured homes offer a genuinely more affordable path to homeownership for many Montana buyers, but the financing side works differently than a standard mortgage in ways that catch people off guard. At Montana Mortgage Company, we help Missoula-area buyers and homeowners understand their options and get matched with the right loan program for their specific home and situation.
Whether you’re buying a manufactured home on land you own, placing one in a manufactured home community, or refinancing a home you already have, the details of how your home is classified make a real difference in which loans you qualify for.
KNOW YOUR HOME TYPE
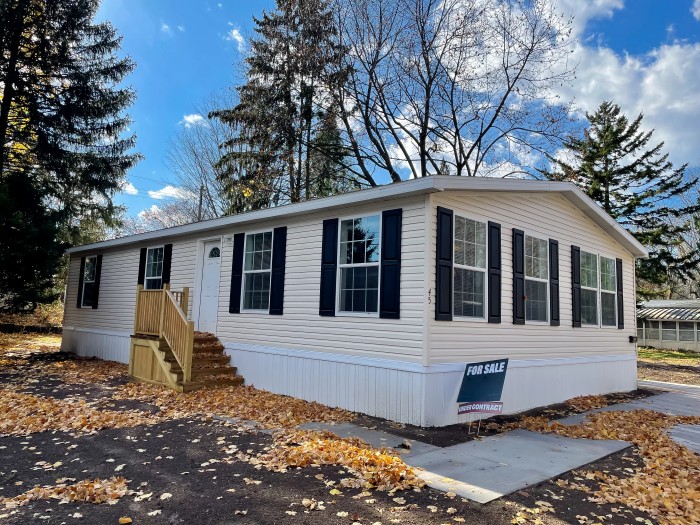
Understanding Manufactured Home Loans: Manufactured, Modular, and Mobile
These three terms get used interchangeably, but they mean different things for financing purposes.
Knowing which category your home actually falls into is the first step in figuring out which financing options apply.
COMPARE FHA FINANCING OPTIONS
FHA Loan for Mobile Home Missoula MT: Title I vs. Title II
If you’re researching an FHA loan for a mobile home in Missoula, MT, FHA actually offers two distinct manufactured home loan programs, and which one applies depends on whether you own the land.
FHA Title II loans treat the manufactured home as real property, the same way FHA treats a site-built house. To qualify, the home must be permanently affixed to a foundation that meets HUD’s Permanent Foundations Guide, and you need to own or be purchasing the land it sits on. Lenders also commonly require an affidavit of affixture to show the home is permanently attached to owned land, and permanent affixation usually means the towing axles, wheels, and hitch have been removed. Title II loans follow the standard FHA county loan limit, $541,287 for most areas in 2026, up to $1,249,125 in designated high-cost counties, and allow terms up to 30 years.
FHA Title I loans are personal property (chattel) loans for the home itself, and they don’t require you to own the land. This makes Title I a common path for buyers placing a home in a manufactured home community on a leased lot; HUD generally requires the lease to extend at least three years beyond the loan’s maturity date. Title I loan limits were substantially raised in a 2024 HUD update after staying flat for more than 15 years, though the exact current caps vary depending on whether you’re financing the home alone, the home and lot together, or a single-section versus multi-section home, so it’s worth getting the current figures directly from Montana Mortgage Company rather than relying on a number found online. Title I loan terms also run shorter than Title II, generally up to 20 years for a single-section home and 25 years for a multi-section home.
Both programs require the home to have been built after June 15, 1976, and typically follow standard FHA terms otherwise: as little as 3.5% down with a 580 credit score, or 10% down with a score between 500 and 579.
A MORE ACCESSIBLE PATH TO OWNERSHIP
Why Choose a Manufactured Home Loan in Missoula, MT
Missoula’s housing costs have climbed in recent years, and Montana’s manufactured housing market has seen steady growth as more residents look for practical paths to ownership.
Manufactured homes offer a real path to homeownership for buyers who might otherwise be priced out of the local market, while often providing more land or outdoor space at a lower cost than many site-built alternatives. Working with a lender who understands both the local real estate landscape and the specific requirements of manufactured home financing, foundation standards, land ownership questions, and which loan program actually fits, helps you avoid surprises partway through the process.

YOUR FINANCING ROADMAP
Steps to Secure Your Manufactured Home Loan
EXPLORE MORE LOAN OPTIONS
Financing Options Beyond FHA
FHA isn’t the only path for manufactured home financing. Veterans and eligible service members may be able to use a VA loan for a qualifying manufactured home; see our VA loans page for the specifics. Buyers in qualifying rural areas around Missoula may have access to USDA financing as well. If you have stronger credit (around 700 or higher) and a larger down payment, conventional financing sometimes offers better terms than FHA for a manufactured home, so it’s worth comparing before assuming FHA is automatically the right fit. Montana Mortgage Company can walk through which option actually makes sense for your credit profile and down payment.

LOCAL GUIDANCE FOR MANUFACTURED HOME BUYERS
Local Expertise You Can Rely On
Montana Mortgage Company brings knowledge of the Missoula, MT real estate market together with the specific requirements manufactured home financing involves, from foundation standards to land classification questions, helping you avoid the pitfalls that catch buyers off guard when a lender isn’t familiar with these loan types.
YOUR NEXT STEP IN MANUFACTURED HOME FINANCING
Contact Montana Mortgage Company Today
If you’re exploring a manufactured home loan or an FHA loan for a mobile home in Missoula, MT, Montana Mortgage Company is here to help. Reach out to Montana Mortgage Company today to talk through your specific situation and figure out which financing path fits.