
Construction Loan Missoula MT

Financing to build from the ground up works differently than a standard mortgage. Montana Mortgage Company helps Missoula buyers structure a construction loan, including a construction-to-permanent loan with a single closing, that releases funds in stages as your build progresses.

10+ Years Lending Experience
·Licensed Montana Loan Originator
·Direct Access, No Call Centers
Local & Direct

You call Scott, not a queue

Full Loan Menu

FHA, VA, USDA & more

From Start to Close

No rotating representatives

Montana Owned & Based

Statewide service

FINANCE YOUR HOME BUILD

Construction Loans and Construction-to-Permanent Financing in Missoula, MT

Building your home in Missoula, MT is one of the more rewarding paths to homeownership, whether you’re envisioning a custom craftsman in the foothills or a modern build near the Clark Fork River. Securing the right financing is the foundation of bringing that plan to life. At Montana Mortgage Company, we work with construction loans built for Montana home buyers who need terms that account for land acquisition, seasonal building timelines, and the realities of Missoula’s real estate landscape.

A construction loan works differently than financing you’d use to buy an existing home, and understanding that difference upfront helps you plan the whole project with fewer surprises.

HOW CONSTRUCTION FINANCING WORKS

Understanding the Construction Loan Process

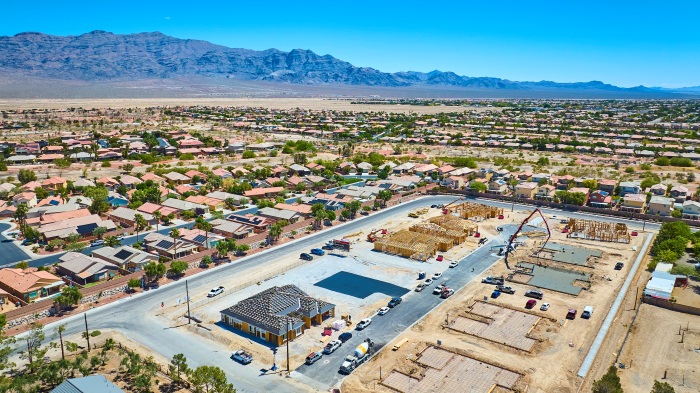
Many borrowers are surprised to learn that construction loans work quite differently from traditional mortgages. Rather than a lump-sum payment, funds are disbursed in stages, commonly called “draws,” as your project hits key milestones. This structure protects both the borrower and the lender by keeping money aligned with actual construction progress.
You’ll work with our team, including loan officers and, where appropriate, mortgage brokers, to review your financial profile, discuss the scope of your build, and determine how much you’re eligible to borrow. To prepare for approval and meet credit qualifications, you’ll need to provide details such as builder contracts, architectural plans, project timelines, proof of stable income, a debt-to-income ratio below 45%, and an appraisal based on the projected completed value of the home.

Once approved, your construction loan is activated, and funds are released incrementally as your builder completes designated phases. In Missoula, it’s worth accounting for local building codes, environmental regulations, and seasonal factors that can affect your construction timeline.

Many construction loans convert into a long-term mortgage once the home build is complete. This “construction-to-permanent” structure can help cover the transition from construction financing to long-term financing without a second closing, saving time and money compared to closing on two separate loans so you do not have to pay a second set of closing costs.

LOCAL BUILDING KNOWLEDGE

Local Expertise and Knowledge

Working with a lender familiar with the Missoula, MT market makes a real difference for a construction loan. Montana Mortgage Company stays informed on regional construction trends, material costs, land availability, and local permit requirements, knowledge that directly benefits your loan experience. Building in Missoula comes with specific considerations, from seasonal weather windows to local zoning, that a lender should understand going in.

COMPARE CONSTRUCTION LOAN OPTIONS

Construction Loan Types: Find the Best Fit for Your Needs

Not all construction loans are the same, and the right option depends on your financial situation, risk tolerance, and building goals.
A fixed-rate construction loan locks in your interest rate for the duration of the loan, and some programs can lock that rate for an extended period — up to eight years — which can be a good fit if you prefer predictable payments, want protection against rising rates during a longer build, and meet the loan-to-value guidelines for that option.

An adjustable-rate construction loan typically offers a lower initial rate, which can reduce costs during the construction phase. This can suit borrowers who expect to convert to a permanent mortgage quickly or who are comfortable with some rate variability in exchange for initial savings.

This combines your construction financing and permanent mortgage into a single product with one closing, a popular choice among Missoula buyers building a new home for a primary residence. One-Time Close Loans may also be available for more than a standard single-family build, including modular homes where program guidelines allow. Because this structure carries its own advantages worth understanding in more depth, see the dedicated section below.

If a 20-25% down payment isn’t realistic for your situation, FHA and VA one-time-close construction loans offer lower or no down payment for buyers who qualify. Depending on the program, manufactured homes may also be eligible; see our FHA loans and VA loans pages for the specifics on each program.

ONE LOAN FROM BUILD TO HOME

Construction-to-Permanent Loan Missoula MT: One Loan, One Closing

A construction-to-permanent loan in Missoula, MT, also called a one-time close construction loan, combines your construction financing and your long-term mortgage into a single loan with a single closing, rather than closing once for construction and again to refinance into permanent financing. Depending on the program, it can also fund the project from lot purchase through final completion.

The biggest practical difference between this and a two-time close structure comes down to when your rate gets locked. With a one-time close, your permanent mortgage rate is typically locked at the initial closing, before construction even begins, and that same rate carries through into your permanent mortgage once the home is finished. Eligible borrowers may also purchase land as part of the overall financing structure. That protects you if rates rise during the build, though it also means you’re not positioned to benefit if rates happen to fall in the meantime, short of refinancing later. A two-time close structure works the other way: you lock your permanent rate at the second closing, after construction wraps up, which exposes you to rate movement in either direction during the build.

The other commonly cited advantage is cost. Avoiding a second closing typically saves somewhere in the range of $3,000 to $7,000 in duplicate closing costs, though the real number depends on your specific loan size and the fees your lender charges, so it’s worth getting an actual comparison rather than assuming the savings automatically apply.

Montana Mortgage Company can walk through whether a one-time close construction-to-permanent loan or a two-time close structure makes more sense for your specific project and risk tolerance.

GET READY TO APPLY

Preparing for Your Construction Loan Application: Tips for Success

Getting approved for a construction loan takes a bit more preparation than a standard mortgage, and the right prep can vary based on your unique needs.

  • Review your credit profile. Most conventional construction lenders look for a credit score of 680 or higher. Review your credit report in advance and address any discrepancies, especially if you are preparing for your first home build.

  • Gather financial documentation. Be prepared to provide income verification, tax returns, bank statements, and information about existing debts and assets.

  • Secure a licensed builder. Lenders want confidence your project will be completed professionally. Having a vetted, licensed contractor in place before applying demonstrates project readiness.

  • Prepare your building plans. Detailed architectural plans and a realistic project budget are essential parts of a strong application, including whether you will need a separate land loan before construction financing.

  • Plan your down payment. Construction loans generally require a higher down payment than traditional mortgages. Many lenders require 10% to 20% of the total project cost, while some conventional options may require more depending on the program and borrower profile. If you already own the land, its appraised equity can often count toward that down payment.

  • Understand local permitting timelines. Missoula has its own permitting and environmental review processes that can affect your project timeline, so it helps to build that into expectations with your lender early.

FINANCING BUILT AROUND YOUR PROJECT

Customizable Loan Solutions

Financing should fit your project, not the other way around. Montana Mortgage Company can match construction loan programs to the specific needs of your build, whether you’re constructing a modest starter home or planning your next home as a custom build. With construction lending expertise, the company offers flexible terms and repayment plans designed around your project. Flexible draw schedules and rate structures mean you stay in control of your finances from breaking ground to final walk-through.

START YOUR HOME BUILD WITH CONFIDENCE

Contact Montana Mortgage Company Today

If you’re ready to build your home in Missoula, MT, reaching out to Montana Mortgage Company is the first step toward discussing the right construction loan structure. Contact Montana Mortgage Company today to schedule a consultation and talk through your construction loan options.

Frequently Asked Questions

Unlike traditional mortgages that provide a lump sum to purchase an existing home, construction loans disburse funds incrementally as your build progresses. They’re typically short-term and interest-only during construction, then convert to a permanent mortgage upon completion.

Missoula’s real estate environment includes factors like seasonal construction windows, local zoning regulations, and environmental land-use considerations that can influence your loan timeline and structure. Working with a lender familiar with these nuances is a real advantage.

Most construction loans are structured for borrowers building a primary residence, though some programs may accommodate second homes. Montana Mortgage Company can help you explore the right loan options for your specific goals.

Construction loan rates typically run higher than standard mortgage rates given the added risk of financing an unfinished home, and even a small difference in rate can meaningfully affect your total project cost. Because rates change based on market conditions and your credit profile, Montana Mortgage Company can provide current numbers for your specific situation.

Missoula’s real estate market includes seasonal building windows, local permitting timelines, and land availability that can all affect your construction schedule and, in turn, your loan structure. Planning around these factors upfront, rather than after your loan is already in motion, generally leads to a smoother build.

Start with a realistic budget for both land and construction, review your credit and down payment position, and secure a licensed builder before applying. From there, Montana Mortgage Company can help match the right construction loan structure, one-time close or two-time close, to your specific project.

Yes. Once the build is complete and the loan converts, it functions as a standard home loan, with regular principal and interest payments over a typical 15- or 30-year term, the same as if you’d purchased an existing home.

Yes, a single family home is the most common property type financed through a construction loan. Some programs may also accommodate other property types, so it’s worth confirming eligibility for your specific project with Montana Mortgage Company.

Both are legitimate options for financing a build in Montana, and terms can vary by lender and by the specifics of your project. Rather than compare on assumptions, it’s worth getting an actual quote from Montana Mortgage Company to see how the rate, down payment requirements, and closing process stack up for your situation.

A one-time close construction loan locks your permanent rate at the start and converts automatically when the build is done, with a single closing. A two-time close structure closes the construction loan first, then requires a second closing to convert to permanent financing, which means a second rate lock and a second round of closing costs. Depending on the loan program and down payment, private mortgage insurance may apply differently between these two structures.

Proof and Trust

Montana Mortgage Company helps homebuyers throughout Missoula and the greater Montana area finance new construction from groundbreaking through move-in.